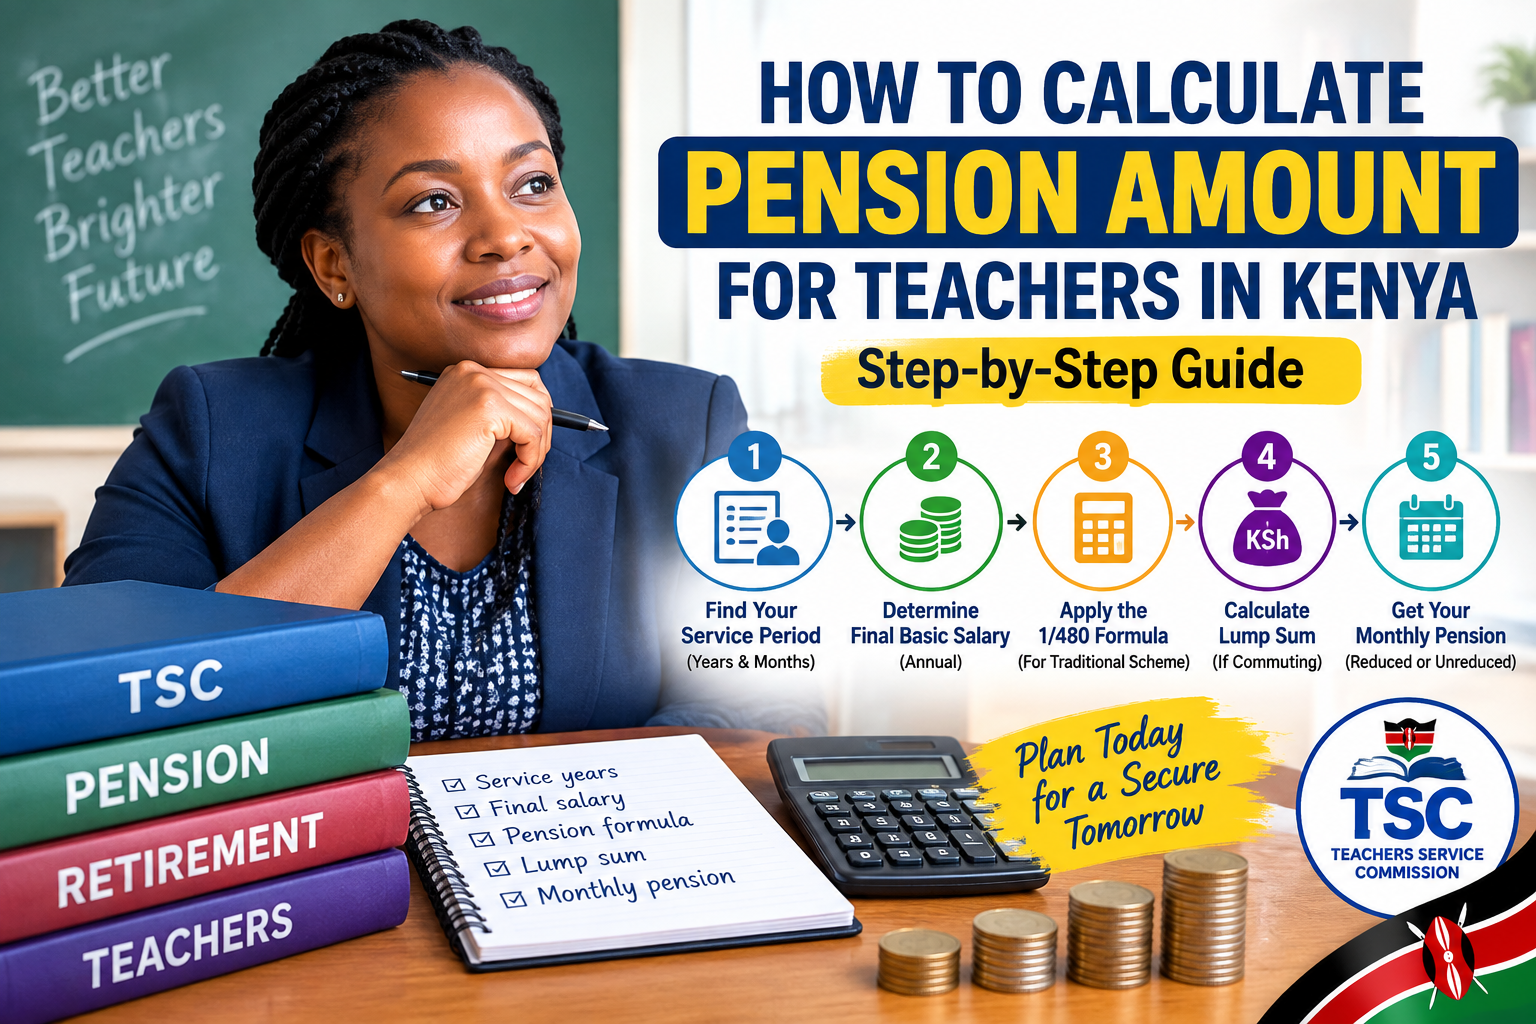
How to Calculate Pension Amount for Teachers in Kenya: Step-by-Step Guide
Calculating a teacher’s pension can seem complicated because the amount depends on factors such as years or months of pensionable service, final pensionable salary, the pension scheme you belong to, and whether you choose to commute part of your pension into a lump sum.
For teachers employed by the Teachers Service Commission (TSC) in Kenya, it is particularly important to distinguish between the old defined-benefit pension arrangement and the Public Service Superannuation Scheme (PSSS), which is a contributory defined-contribution scheme that commenced on 1 January 2021.
This guide explains the calculation step by step, with examples and formulas you can use to estimate retirement benefits.
Important: Pension calculations can depend on your employment history and applicable scheme rules. The examples below are illustrations, not an official pension quotation from TSC or the National Treasury.
What Is a Teacher’s Pension?
A pension is a retirement benefit paid to an eligible teacher after leaving employment under qualifying retirement conditions.
For teachers covered by the traditional government defined-benefit pension arrangement, the pension is principally determined by:
- Pensionable service
- Final pensionable emoluments
- The applicable pension accrual factor
- Whether the teacher commutes part of the pension into a lump sum
The Public Service Superannuation Scheme also covers teachers employed by TSC, but it works differently because it is a defined-contribution scheme.
Therefore, the first question when estimating pension is:
Which pension scheme covers the teacher?
This distinction is extremely important.
Understand the Two Main Pension Arrangements
The Traditional Defined-Benefit Pension Scheme
Under the traditional pension formula applicable to qualifying service, the benefit is based on the teacher’s pensionable service and final pensionable emoluments.
The official TSC regulations give the pension calculation using a 1/480 accrual factor.
The Public Service pension handbook similarly states that benefits under the current pension arrangement are calculated using:
- Length of service
- Final pensionable emoluments, meaning annual basic salary at retirement
- A pension accrual factor of 1/480.
Understand the Public Service Superannuation Scheme
The Public Service Superannuation Scheme (PSSS) is different.
It is a defined-contribution retirement scheme established under the Public Service Superannuation Scheme Act and commenced on 1 January 2021. Teachers employed by TSC are among the groups covered by the scheme.
For a defined-contribution scheme, the retirement benefit isn’t calculated simply by taking the final salary and multiplying it by years of service.
Instead, the eventual benefit is connected to contributions and investment performance.
The PSSS explains the benefit broadly as:
Retirement benefit = Employer contributions + Employee contributions + Investment income
subject to the applicable scheme rules.
This means a teacher in PSSS should not automatically use the old 1/480 formula to estimate the entire retirement benefit.
The Old Pension Formula for Teachers
For teachers whose pension is calculated under the traditional defined-benefit arrangement, the official TSC formula provides three important calculations:
A. Unreduced monthly pension
The formula is:
Monthly Pension = (Number of Months Worked ÷ 480) × Annual Basic Salary ÷ 12
This represents the monthly pension when the teacher does not commute part of the pension into a lump sum.
Step One: Calculate Total Months of Service
The first thing you need is the teacher’s total pensionable service.
The TSC formula uses months, not simply years.
For example:
- 10 years = 120 months
- 20 years = 240 months
- 25 years = 300 months
- 30 years = 360 months
- 35 years = 420 months
- 40 years = 480 months
Formula
Total months of service = Number of completed years × 12
For example, if a teacher has completed 30 years:
30 × 12 = 360 months
If the service period contains additional completed months, those should also be included in the calculation.
Step Two: Determine the Final Pensionable Salary
The next figure is the teacher’s annual basic salary at retirement, where the applicable defined-benefit formula requires annual basic salary.
For example, suppose the teacher’s final monthly basic salary is:
KSh 80,000
Annual basic salary would be:
KSh 80,000 × 12 = KSh 960,000
So:
Annual pensionable salary = KSh 960,000
Be careful here.
The pension formula should not automatically be based on the teacher’s entire gross monthly pay.
Allowances and other payments should not simply be added to basic salary unless the applicable pension rules specifically treat them as pensionable emoluments.
The Public Service pension handbook describes final pensionable emoluments for this calculation as the annual basic salary at the time of retirement.
Step Three: Apply the 1/480 Formula
Now we can calculate the annual pension.
The basic formula is:
Annual Pension = Months of Pensionable Service × Annual Basic Salary ÷ 480
Let’s use an example.
Suppose:
- Service = 30 years
- Months of service = 360
- Final monthly basic salary = KSh 80,000
- Annual basic salary = KSh 960,000
Calculation:
360 ÷ 480 = 0.75
Then:
0.75 × KSh 960,000 = KSh 720,000 per year
Therefore:
Annual pension = KSh 720,000
To convert this into a monthly pension:
KSh 720,000 ÷ 12 = KSh 60,000
Estimated unreduced monthly pension:
KSh 60,000 per month
This is an illustration using the statutory formula, not an official individual pension assessment.
A Simpler Way to Understand the Formula
The same calculation can be written as:
Monthly Pension = Months Worked × Annual Basic Salary ÷ 480 ÷ 12
Or:
Monthly Pension = Months Worked × Monthly Basic Salary ÷ 480
For example:
360 × KSh 80,000 ÷ 480
= KSh 60,000
This shortcut works because annual salary is simply monthly basic salary multiplied by 12 and then divided by 12 when converting annual pension back to monthly pension.
Example: Teacher With 20 Years of Service
Suppose a teacher has:
- 20 years of pensionable service
- 240 months of service
- Final monthly basic salary of KSh 70,000
Annual basic salary:
KSh 70,000 × 12 = KSh 840,000
Pension:
240 ÷ 480 × KSh 840,000
= KSh 420,000 annually
Monthly pension:
KSh 420,000 ÷ 12
= KSh 35,000
Estimated unreduced pension:
KSh 35,000 per month
Example: Teacher With 25 Years of Service
Consider another teacher with:
- 25 years of service
- 300 months
- Final monthly basic salary of KSh 90,000
Annual basic salary:
KSh 90,000 × 12 = KSh 1,080,000
Annual pension:
300 ÷ 480 × KSh 1,080,000
= KSh 675,000
Monthly pension:
KSh 675,000 ÷ 12
= KSh 56,250
Estimated unreduced monthly pension:
KSh 56,250
Example: Teacher With 35 Years of Service
Suppose:
- Service = 35 years
- Months = 420
- Final basic salary = KSh 100,000 per month
Annual basic salary:
KSh 100,000 × 12 = KSh 1,200,000
Annual pension:
420 ÷ 480 × KSh 1,200,000
= KSh 1,050,000
Monthly pension:
KSh 1,050,000 ÷ 12
= KSh 87,500
Estimated unreduced monthly pension:
KSh 87,500
How to Calculate the Pension Lump Sum
One of the most important features of the traditional TSC pension calculation is the option to commute a portion of the pension.
Under the TSC formula, a teacher may commute one-quarter of the pension entitlement and receive a lump sum calculated using a factor of 20.
The formula is:
Lump Sum = Months Worked ÷ 480 × Annual Basic Salary × 1/4 × 20
Let’s use the earlier example:
- 360 months
- Annual basic salary = KSh 960,000
First calculate annual pension:
360 ÷ 480 × 960,000 = KSh 720,000
One-quarter:
KSh 720,000 × 1/4 = KSh 180,000
Multiply by 20:
KSh 180,000 × 20 = KSh 3,600,000
Estimated lump sum:
KSh 3.6 million
This calculation is based on the official formula for the traditional pension arrangement.
How the Lump Sum Affects Monthly Pension
The lump sum does not simply come from nowhere.
The teacher is exchanging part of the pension entitlement for an upfront payment.
The TSC formula therefore provides a reduced monthly pension after the one-quarter commutation.
The reduced monthly pension is calculated using three-quarters of the original pension entitlement.
Using our example:
Original monthly pension:
KSh 60,000
Three-quarters:
KSh 60,000 × 3/4
= KSh 45,000
Estimated reduced monthly pension:
KSh 45,000
And the estimated lump sum is:
KSh 3.6 million
So the illustration becomes:
| Benefit | Amount |
|---|---|
| Unreduced monthly pension | KSh 60,000 |
| Commuted lump sum | KSh 3,600,000 |
| Reduced monthly pension after commutation | KSh 45,000 |
Again, this is an example based on the statutory formula, not a personal pension award.
What Does “Commutation” Mean?
Commutation means exchanging part of your future pension for a lump-sum payment.
For example, instead of receiving the entire pension as a monthly payment, an eligible teacher may choose to receive a lump sum representing the commuted portion and then receive a lower monthly pension.
The TSC regulations provide for commuting up to one-quarter of the pension entitlement under the applicable arrangement.
This creates two major components:
1. Lump-sum retirement benefit
A one-time payment.
2. Reduced monthly pension
The continuing pension after commutation.
Example of Full Calculation From Start to Finish
Let’s put everything together.
Assume:
Teacher’s final basic salary: KSh 100,000 per month
Years worked: 30 years
Months worked: 30 × 12 = 360
Step 1: Annual salary
KSh 100,000 × 12
= KSh 1,200,000
Step 2: Calculate annual pension
360 ÷ 480 × KSh 1,200,000
= KSh 900,000
Step 3: Calculate unreduced monthly pension
KSh 900,000 ÷ 12
= KSh 75,000
Step 4: Calculate one-quarter pension
KSh 75,000 × 1/4
= KSh 18,750
Step 5: Calculate lump sum
KSh 18,750 × 12 × 20
= KSh 4,500,000
Alternatively:
KSh 900,000 × 1/4 × 20
= KSh 4,500,000
Step 6: Calculate reduced monthly pension
KSh 75,000 × 3/4
= KSh 56,250
Illustration summary
Lump sum: KSh 4.5 million
Reduced monthly pension: KSh 56,250
Unreduced monthly pension: KSh 75,000
Pension Calculation Table for Teachers
The following table provides illustrations assuming different years of service and different final monthly basic salaries.
| Years of Service | Final Basic Salary | Estimated Monthly Pension* |
|---|---|---|
| 20 years | KSh 60,000 | KSh 30,000 |
| 20 years | KSh 80,000 | KSh 40,000 |
| 25 years | KSh 80,000 | KSh 50,000 |
| 25 years | KSh 100,000 | KSh 62,500 |
| 30 years | KSh 80,000 | KSh 60,000 |
| 30 years | KSh 100,000 | KSh 75,000 |
| 35 years | KSh 100,000 | KSh 87,500 |
| 35 years | KSh 120,000 | KSh 105,000 |
| 40 years | KSh 100,000 | KSh 100,000 |
| 40 years | KSh 120,000 | KSh 120,000 |
*Illustrations based on the traditional 1/480 defined-benefit formula and assuming the stated salary is the applicable final pensionable basic salary.
What Is the Maximum Service Used in the Formula?
The TSC regulations explain that 480 months represents 40 years, based on 12 months × 40 years.
Therefore, 40 years of pensionable service corresponds to:
480 ÷ 480 = 1
So, if a teacher had 40 years of qualifying service, the formula would produce an annual pension equal to the applicable annual pensionable salary before any commutation.
When Can a TSC Teacher Retire?
Retirement conditions depend on the circumstances and applicable regulations.
TSC states that compulsory retirement applies at age 60, with a retirement notice normally issued two years before the retirement date.
TSC also provides for voluntary retirement.
Under its published guidance, a teacher may apply for voluntary retirement after attaining 50 years of age and completing 10 years of continuous service on permanent and pensionable terms.
The regulations also provide for retirement on grounds including age, public interest and medical grounds.
Why Your Payslip Matters
A teacher trying to estimate pension should gather several records before doing the calculation.
Important information includes:
- Date of first appointment
- Date of retirement
- Total pensionable service
- Promotion history
- Final job grade
- Final basic salary
- Retirement notice
- Pension scheme membership
- Previous government service
- Any transferred service
- Relevant pension correspondence
Your payslip can help establish the salary information, but the final pension calculation is an administrative process based on official employment records.
TSC’s online services also include Pension Status, which allows users to view pension claims delivered to the Treasury.
Why Promotion Can Affect Pension
Promotion can affect pension calculations because the traditional formula uses the applicable final pensionable emoluments.
For example, consider two teachers with the same service period:
Teacher A
- 30 years of service
- Final basic salary: KSh 70,000
Estimated monthly pension:
30 × 70,000 ÷ 40
= KSh 52,500
Teacher B
- 30 years of service
- Final basic salary: KSh 100,000
Estimated monthly pension:
30 × 100,000 ÷ 40
= KSh 75,000
The difference comes from the different final pensionable salaries.
This illustrates why maintaining accurate promotion and salary records is important when preparing for retirement
What If You Have 10, 20, or 30 Years of Service?
Using the simplified traditional formula:
Monthly pension = Years of service ÷ 40 × final monthly basic salary
This is mathematically equivalent to the 1/480 formula when service is expressed in complete years.
10 years
10 ÷ 40 = 25%
So the illustration is:
25% × final basic salary
20 years
20 ÷ 40 = 50%
30 years
30 ÷ 40 = 75%
40 years
40 ÷ 40 = 100%
This is a useful way of understanding the underlying accrual factor, although an actual pension claim should use the official service records and applicable rules.
What Happens If You Choose Not to Commute?
If an eligible teacher does not commute the pension, the traditional TSC formula describes the resulting payment as the unreduced monthly pension, with no lump-sum commutation payment under that formula.
For example:
If the calculated pension is:
KSh 75,000 per month
the teacher who does not commute would receive the unreduced amount under the applicable arrangement.
If the teacher commutes one-quarter:
Lump sum = KSh 4.5 million
and the illustrated monthly pension becomes:
KSh 56,250
The choice therefore involves a trade-off between an upfront lump sum and a higher continuing monthly pension.
Important Difference Between Pension and Gratuity
The terms pension and gratuity are sometimes used interchangeably in everyday conversations, but they are not necessarily the same thing.
Pension
A recurring retirement payment, usually paid monthly.
Gratuity or lump sum
A payment made as a single amount under the applicable rules.
For teachers covered by the traditional formula, the commuted pension can produce a lump-sum payment.
The TSC regulations also contain separate provisions concerning gratuity in particular circumstances.
Therefore, when asking “How much is my pension?”, it is useful to clarify whether you mean:
- Monthly pension
- Retirement lump sum
- Both
- Other retirement benefits
What About Teachers Who Joined the New Pension Scheme?
This is one of the most important issues for teachers today.
The Public Service Superannuation Scheme began on 1 January 2021 and covers teachers employed by TSC.
The transition rules state that employees below age 45 joined the new scheme automatically from 1 January 2021, while employees aged 45 and above who did not opt into the new scheme during the specified transition period remained in the old defined-benefit scheme.
The transition arrangement also recognizes service accumulated under the old scheme for members who moved into the new scheme.
Consequently, not every TSC teacher should calculate their entire retirement benefit using the 1/480 formula.
Your membership history matters.
How PSSS Benefits Are Different
Under a defined-contribution scheme, the final retirement benefit depends on accumulated contributions and investment income rather than simply applying a fixed pension formula to final salary.
The PSSS describes itself as a defined-contribution fund.
This means two teachers with similar salaries may not necessarily have identical retirement balances if their contribution histories differ.
Factors can include:
- Employee contributions
- Employer contributions
- Length of membership
- Investment income
- Voluntary additional contributions
- Applicable retirement rules
- Previous recognized service
Therefore, if you are a PSSS member, you should obtain your actual member statement rather than relying exclusively on the old pension calculator.
A Practical Pension Calculation Checklist
Before estimating your retirement benefit, collect the following information:
Personal employment information
☐ Date of first appointment
☐ Date of retirement
☐ Total years of service
☐ Total months of pensionable service
Salary information
☐ Current basic salary
☐ Final basic salary
☐ Promotion history
☐ Final job grade
Pension information
☐ Pension scheme
☐ Pension statement
☐ Previous government service
☐ Recognized transferred service
☐ Whether you intend to commute pension
This information will make your estimate much more accurate.
Step-by-Step Teacher Pension Calculator
You can use the following process to make a quick estimate under the traditional defined-benefit formula.
Step 1
Find your final monthly basic salary.
Example:
KSh 100,000
Step 2
Find your completed years of pensionable service.
Example:
30 years
Step 3
Convert years into months.
30 × 12 = 360 months
Step 4
Calculate annual basic salary.
KSh 100,000 × 12 = KSh 1,200,000
Step 5
Calculate annual pension.
360 ÷ 480 × KSh 1,200,000 = KSh 900,000
Step 6
Calculate monthly pension.
KSh 900,000 ÷ 12 = KSh 75,000
Step 7
If applicable, calculate the commuted lump sum.
KSh 900,000 × 1/4 × 20 = KSh 4,500,000
Step 8
Calculate reduced monthly pension.
KSh 75,000 × 3/4 = KSh 56,250
Common Mistakes When Calculating Teacher Pension
Mistake 1: Using gross salary
A common mistake is taking the total gross salary and applying the pension formula.
The traditional public-service formula refers to final pensionable emoluments/annual basic salary, so you should establish which components are actually pensionable.
Mistake 2: Forgetting months
The official formula uses months.
For example:
30 years = 360 months, not 30.
Mistake 3: Ignoring pension scheme membership
A teacher who is in the PSSS should not automatically calculate the entire retirement benefit using the old 1/480 formula.
Mistake 4: Confusing lump sum with monthly pension
The lump sum and monthly pension are separate components of the retirement benefit under the traditional commutation arrangement.
Mistake 5: Assuming every teacher gets the same percentage
Pension depends on factors including service and pensionable salary, and newer contributory arrangements work differently.
Frequently Asked Questions About Teacher Pension in Kenya
How is TSC pension calculated?
For qualifying service under the traditional defined-benefit arrangement, the official formula uses:
Pension = Months of pensionable service × Annual basic salary ÷ 480
The annual amount can then be divided by 12 to obtain the monthly pension.
How much pension does a teacher get after 30 years?
Under the traditional formula, 30 years represents 360 months.
Therefore:
360 ÷ 480 = 75%
The resulting pension depends on the applicable final pensionable salary.
For example, with a KSh 100,000 monthly basic salary, the illustration gives approximately KSh 75,000 per month before any commutation.
How is the teacher pension lump sum calculated?
Under the traditional TSC formula:
Lump Sum = Months Worked ÷ 480 × Annual Basic Salary × 1/4 × 20
Can a teacher retire at 50?
TSC’s published voluntary-retirement guidance states that a teacher may apply for voluntary retirement at age 50 after completing 10 years of continuous service on permanent and pensionable terms, subject to the applicable process.
What is the compulsory retirement age for TSC teachers?
TSC’s published pension information states that compulsory retirement applies at 60 years.
Is every TSC teacher under the same pension formula?
No. The introduction of the Public Service Superannuation Scheme created a contributory arrangement for public servants, including TSC teachers, and transition arrangements apply.
Final Pension Calculation Formula
For a qualifying teacher under the traditional defined-benefit arrangement, the central formula is:
Annual Pension
Annual Pension = Months of Pensionable Service × Annual Basic Salary ÷ 480
Monthly Pension
Monthly Pension = Months of Pensionable Service × Annual Basic Salary ÷ 480 ÷ 12
Commuted Lump Sum
Lump Sum = Months of Pensionable Service × Annual Basic Salary ÷ 480 × 1/4 × 20
Reduced Monthly Pension
Reduced Monthly Pension = Unreduced Monthly Pension × 3/4
These formulas are set out in the TSC Code of Regulations for Teachers.
Final Thoughts
Calculating a teacher’s pension in Kenya starts with identifying the correct pension scheme.
For the traditional defined-benefit arrangement, the calculation is relatively straightforward:
Pensionable service → final pensionable salary → 1/480 formula → monthly pension → optional commutation calculation.
However, teachers affected by the Public Service Superannuation Scheme need to consider their accumulated contributions and investment income rather than simply applying the old 1/480 formula to their entire career. The PSSS has covered TSC teachers since its commencement in January 2021, with transition provisions for existing public servants.
For an actual retirement claim, the official TSC and pension authorities’ records should be treated as authoritative. TSC also provides an online Pension Status service for tracking pension claims delivered to the Treasury.