How to Plan for a KSh 20,000 Stipend: Survival Guide for Intern Teachers in Kenya
Starting an internship as a teacher can be exciting, but it can also come with serious financial pressure. For many intern teachers in Kenya, a KSh 20,000 monthly stipend has to cover transport, food, rent, communication, personal expenses and sometimes support for family members.
The good news is that KSh 20,000 can be managed more effectively with a realistic budget and disciplined spending habits.
The key is not to treat the stipend like a permanent salary. An internship is a period to gain classroom experience, build your professional record, improve your skills and prepare for the next employment opportunity.
This guide explains how an intern teacher can plan a KSh 20,000 stipend, reduce unnecessary expenses, avoid debt and still put some money aside every month.
Understanding Your KSh 20,000 Stipend
Before spending anything, divide your money according to priorities.
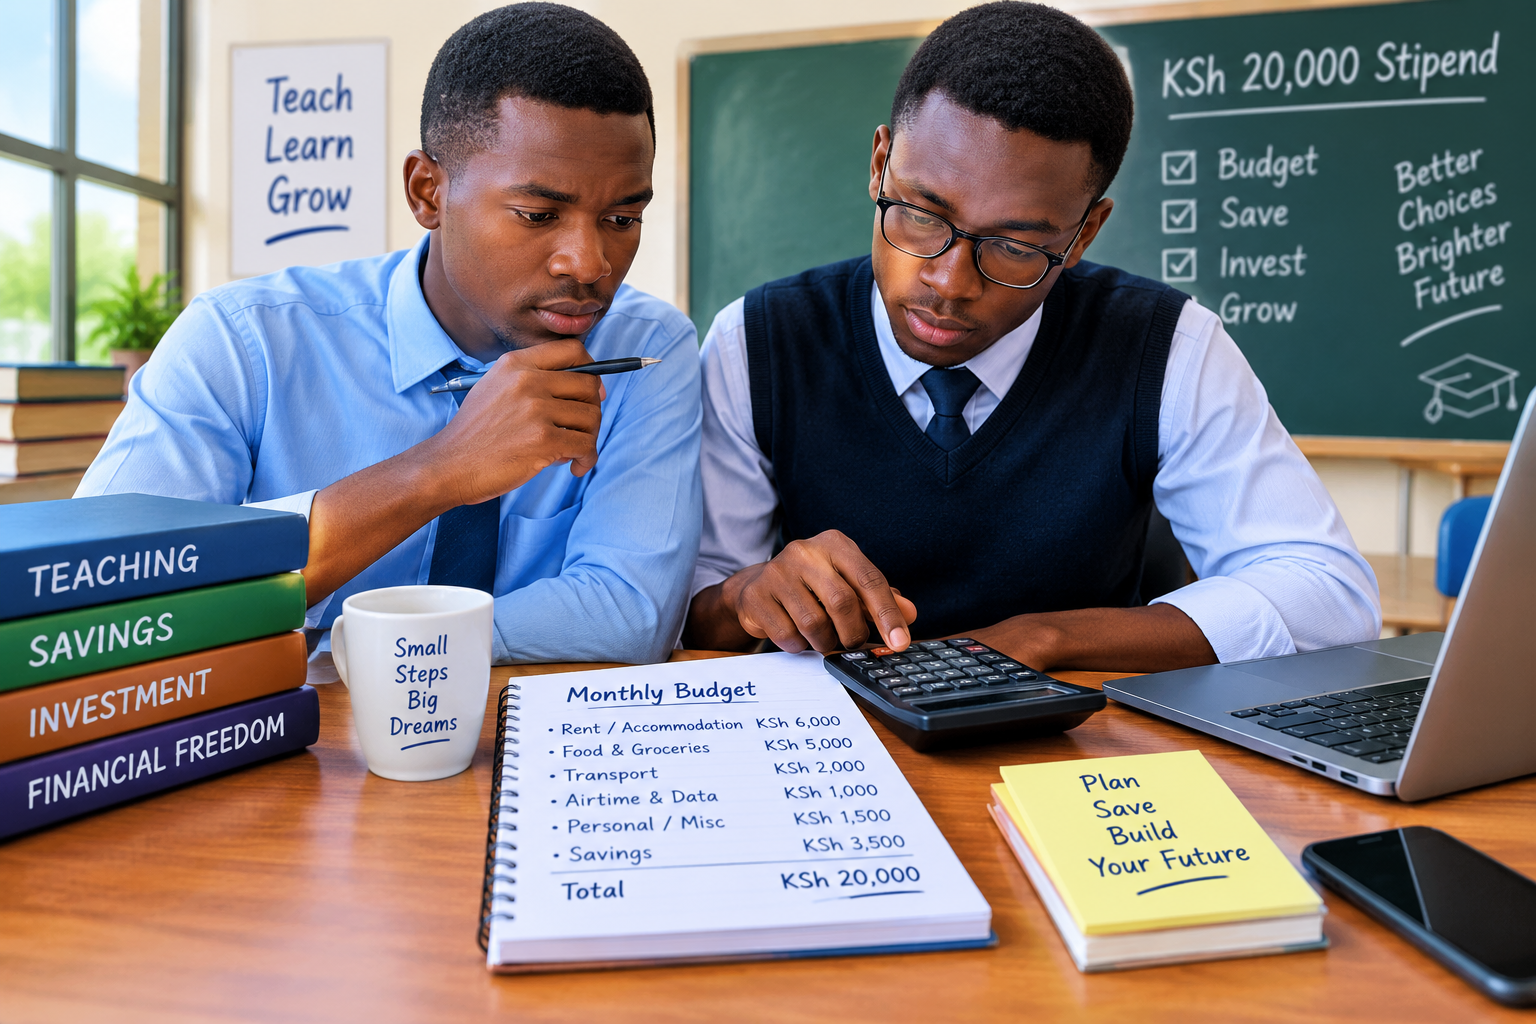
A simple monthly plan could look like this:
| Expense | Suggested Amount |
|---|---|
| Rent and housing | KSh 5,000 |
| Food | KSh 4,000 |
| Transport | KSh 4,000 |
| Savings/emergency fund | KSh 2,000 |
| Airtime/data | KSh 1,000 |
| Personal/household expenses | KSh 2,000 |
| Professional expenses | KSh 1,000 |
| Total | KSh 19,000 |
| Buffer | KSh 1,000 |
This is only a sample. Your actual budget should depend on where you live, how far your school is from home and whether you have family responsibilities.
The most important principle is to budget before spending.
1. Pay Yourself First
One of the biggest mistakes people make when earning a small income is waiting until the end of the month to save.
Usually, there is nothing left.
Instead, save immediately after receiving your stipend.
For example:
KSh 20,000 – KSh 2,000 savings = KSh 18,000 available for expenses.
If KSh 2,000 is difficult, start with KSh 1,000.
The objective is to develop the habit.
If you save KSh 2,000 every month for 12 months:
KSh 2,000 × 12 = KSh 24,000.
That money can eventually help you handle emergencies, professional development or a transition between internship and another job opportunity.
2. Keep Rent Under Control
Rent can destroy a small income if you are not careful.
If you receive KSh 20,000, spending KSh 10,000 or KSh 12,000 on rent leaves very little for everything else.
Where possible, consider:
- A bedsitter or affordable single room
- Shared accommodation
- Living with relatives temporarily
- Housing closer to the school
- A location where transport costs are low
- Moving to a cheaper area if your current rent is excessive
Remember that cheap rent is not always cheap living.
For example, paying KSh 3,000 rent but spending KSh 5,000 on transport every month may be more expensive than paying KSh 5,000 rent close to school.
Look at the total cost of housing plus transportation.
3. Control Transport Costs
Transport can quietly consume a large percentage of an intern teacher’s stipend.
If you spend:
KSh 200 per day × 22 working days = KSh 4,400 per month.
That is more than one-fifth of a KSh 20,000 stipend.
Consider practical alternatives:
- Walk where the distance is manageable and safe.
- Use public transport instead of expensive alternatives.
- Share rides with colleagues where appropriate.
- Find accommodation closer to school.
- Combine errands to reduce unnecessary trips.
- Avoid travelling unnecessarily during weekdays.
Even reducing transport expenditure by KSh 50 per day can make a difference over a month.
4. Prepare Your Own Food
Buying food every day can seriously affect a KSh 20,000 budget.
A teacher who buys breakfast and lunch every working day may spend thousands of shillings without realizing it.
For example:
- Breakfast: KSh 80
- Lunch: KSh 150
- Occasional tea/snacks: KSh 50
That is approximately KSh 280 per working day.
Over 22 working days:
KSh 280 × 22 = KSh 6,160.
Cooking at home and carrying packed lunch can reduce this considerably.
Consider affordable foods such as:
- Ugali
- Rice
- Beans
- Green vegetables
- Lentils
- Potatoes
- Eggs
- Omena
- Seasonal fruits
- Maize
- Chapati occasionally
The objective is not to eat poorly. It is to eat well without allowing food expenses to consume your entire stipend.
5. Create a Weekly Food Budget
Instead of spending randomly, divide your food money into weekly amounts.
If you allocate KSh 4,000 per month:
KSh 4,000 ÷ 4 = KSh 1,000 per week.
Buy basic supplies in advance where possible.
A weekly food plan might include:
- Breakfast items
- Main meal ingredients
- Vegetables
- Protein
- Drinking water
- Small emergency food allowance
Planning also reduces impulse purchases.
6. Be Careful With Mobile Loans
Mobile loans can become dangerous when used to finance ordinary consumption.
Borrowing KSh 1,000 today may appear harmless. But repeated borrowing can create a cycle where the next stipend is already committed before it arrives.
Avoid borrowing for:
- Entertainment
- Expensive clothes
- Weekend outings
- Alcohol
- Unnecessary electronics
- Betting
- Impulse purchases
If you must borrow because of a genuine emergency, understand the repayment terms and make sure repayment will not destroy your following month’s budget.
7. Avoid Lifestyle Pressure
Intern teachers often work alongside permanent employees and may feel pressure to maintain the same lifestyle.
That can lead to unnecessary spending.
You do not have to:
- Buy expensive clothes every month
- Own the latest smartphone
- Attend every social event
- Contribute beyond your means
- Eat at expensive restaurants
- Upgrade your lifestyle simply because you have started earning
Your internship is a temporary stage.
Focus on building your future rather than impressing people today.
8. Have an Emergency Fund
An emergency fund is especially important for an intern.
Unexpected expenses can include:
- Illness
- Emergency travel
- Family emergencies
- Replacement of a damaged phone
- Professional requirements
- Unexpected accommodation costs
Your first target could be KSh 5,000.
After reaching KSh 5,000, aim for KSh 10,000 and eventually build a larger reserve.
Even saving KSh 1,000–KSh 2,000 monthly can gradually create a financial cushion.
9. Separate Needs From Wants
Before buying something, ask:
Do I need this or do I simply want it?
Needs
- Rent
- Food
- Transport
- Basic communication
- Essential clothing
- Professional requirements
- Emergency expenses
Wants
- New smartphone when your current one works
- Expensive entertainment
- Frequent restaurant meals
- Designer clothing
- Unnecessary subscriptions
- Impulse shopping
This simple distinction can protect your stipend.
10. Budget for Your Teaching Career
Do not spend your entire stipend only on survival.
Allocate a small amount toward professional development.
For example:
KSh 1,000 per month
could be used for:
- Teaching materials
- Printing
- Internet research
- Professional books
- Online learning
- Educational resources
- Professional documents
However, teachers should also avoid unnecessarily paying for materials that the school is responsible for providing. Understand your school’s expectations before spending your own money.
11. Use Your Internship to Build Your Professional Portfolio
Your internship is more than a source of income.
It is an opportunity to build evidence of your teaching experience.
Keep records of:
- Lesson plans
- Schemes of work
- Teaching resources
- Assessments
- Professional development activities
- Classroom management strategies
- Co-curricular activities
- School projects
- Responsibilities assigned to you
- Positive feedback from supervisors where appropriate
Your professional experience can become valuable when applying for future teaching opportunities.
12. Do Not Ignore Professional Networking
Build healthy professional relationships with:
- Senior teachers
- Heads of department
- School administrators
- Other intern teachers
- Education professionals
- Former university classmates
Networking should not mean asking everyone for a job.
Instead, learn from experienced teachers and stay informed about legitimate education and employment opportunities.
13. Avoid Betting as a “Side Income”
One of the most dangerous financial mistakes for someone living on a KSh 20,000 stipend is treating football betting or gambling as an income strategy.
A stipend should be protected because it covers essential expenses.
If you have KSh 500 remaining at the end of the month, turning it into a betting stake does not solve your financial situation.
A better approach is to put spare money toward:
- Savings
- Emergency funds
- Professional development
- A small productive project
- Essential household needs
14. Find a Legitimate Side Hustle Carefully
If your internship schedule allows it and it does not interfere with your teaching responsibilities, you can explore legitimate additional income.
Possible options include:
Tutoring
Private tutoring can use the teaching skills you already possess.
You could offer tutoring in subjects you are qualified to teach, subject to applicable rules and your school’s requirements.
Digital Work
Depending on your skills, you might explore:
- Writing
- Graphic design
- Data entry
- Transcription
- Online tutoring
- Website management
- Educational content creation
Small Business
A small business can also provide additional income if carefully managed.
Examples include:
- Selling educational materials
- Small-scale poultry keeping
- Vegetable farming
- Grocery sales
- Clothing resale
- Other small enterprises suitable for your location
The important thing is to start small and avoid borrowing heavily to launch a business.
15. Use the 24-Hour Rule
Before buying something that is not essential, wait 24 hours.
If you still need it after a day and it fits your budget, consider buying it.
This simple rule can prevent many impulse purchases.
For expensive purchases, extend the waiting period to a week or longer.
16. Track Every Shilling
You cannot control what you do not track.
At the beginning of every month, write down:
Income: KSh 20,000
Then record every expense.
For example:
| Category | Budget | Actual |
|---|---|---|
| Rent | 5,000 | 5,000 |
| Food | 4,000 | 4,300 |
| Transport | 4,000 | 3,800 |
| Savings | 2,000 | 2,000 |
| Airtime/Data | 1,000 | 900 |
| Personal | 2,000 | 1,700 |
| Professional | 1,000 | 700 |
| Buffer | 1,000 | 600 |
At the end of the month, compare your budget with reality.
Then adjust the following month’s plan.
17. A More Aggressive KSh 20,000 Savings Plan
If you have cheap accommodation or live with family, you may be able to save more.
For example:
| Category | Amount |
|---|---|
| Housing | KSh 4,000 |
| Food | KSh 3,500 |
| Transport | KSh 3,500 |
| Savings | KSh 5,000 |
| Airtime/Data | KSh 800 |
| Personal expenses | KSh 1,500 |
| Professional development | KSh 700 |
| Emergency/Buffer | KSh 1,000 |
| Total | KSh 20,000 |
Saving KSh 5,000 monthly would produce:
KSh 60,000 in 12 months, assuming the stipend remains available at that level and the savings are not withdrawn.
For many interns, however, saving KSh 5,000 may not be realistic. There is nothing wrong with starting at KSh 1,000 or KSh 2,000.
Consistency matters.
18. What If You Support Your Family?
Family responsibilities can make a KSh 20,000 stipend much harder to manage.
If you regularly send money home, include it in your budget rather than treating it as an unexpected expense.
For example:
KSh 20,000 income
- Rent: KSh 4,500
- Food: KSh 3,500
- Transport: KSh 3,500
- Family support: KSh 2,000
- Savings: KSh 1,500
- Data/airtime: KSh 800
- Personal expenses: KSh 1,700
- Emergency/professional: KSh 1,500
- Buffer: KSh 1,000
The exact amounts should be adjusted according to individual circumstances.
The important rule is:
Do not destroy your own financial stability in an attempt to solve every financial problem around you.
19. Build a “Transition Fund”
An internship may eventually come to an end.
Instead of waiting until the final month to think about what happens next, create a transition fund.
This money can help with:
- Transport to interviews
- Printing application documents
- Internet bundles
- Professional requirements
- Relocation
- Temporary living expenses
- Further training
Think of your savings as freedom money.
The more money you have available when the internship ends, the more options you have.
20. Plan Your Career While You Are Still an Intern
Do not wait until your internship is ending before thinking about your next step.
During the internship:
- Improve your classroom skills.
- Build your professional portfolio.
- Update your CV.
- Follow legitimate teaching vacancies.
- Improve your digital skills.
- Develop your communication skills.
- Build professional relationships.
- Explore further qualifications where appropriate.
- Keep your documents organized.
- Monitor official announcements from relevant institutions.
The goal is to leave the internship with experience, savings, skills and a plan.
Sample KSh 20,000 Monthly Survival Formula
A simple formula for an intern teacher could be:
50% – Basic needs
KSh 10,000 for rent, food and essential living expenses.
20% – Transport
KSh 4,000.
10% – Savings
KSh 2,000.
10% – Personal and communication
KSh 2,000.
5% – Professional development
KSh 1,000.
5% – Emergency buffer
KSh 1,000.
This is a starting framework rather than a fixed rule.
If your transport costs are lower, move the difference into savings.
If your rent is higher, look for ways to reduce other expenses rather than automatically taking a loan.
10 Financial Rules Every Intern Teacher Should Remember
Rule 1: Budget immediately
Do not start spending before creating a monthly plan.
Rule 2: Save before spending
Even KSh 1,000 matters.
Rule 3: Keep housing affordable
High rent can consume your entire stipend.
Rule 4: Watch transport
Small daily transport expenses can become thousands of shillings.
Rule 5: Cook when possible
Home cooking can significantly reduce food expenditure.
Rule 6: Avoid unnecessary debt
Do not borrow simply to maintain a lifestyle.
Rule 7: Avoid gambling as an income strategy
Protect your limited income.
Rule 8: Invest in yourself
Use the internship to develop professional skills.
Rule 9: Prepare for the next opportunity
Do not assume the internship will automatically solve your long-term career needs.
Rule 10: Live below your income
If you receive KSh 20,000, do not create a KSh 25,000 lifestyle.
Final Thoughts
Managing a KSh 20,000 stipend as an intern teacher in Kenya requires discipline more than complicated financial knowledge.
The first objective should be survival without unnecessary debt.
The second should be building an emergency fund.
The third should be developing your teaching career and preparing for your next employment opportunity.
A useful monthly mindset is:
Earn → Budget → Save → Spend → Track → Improve.
Do not underestimate small savings. Saving KSh 1,000 every month may look insignificant, but developing the habit while earning a modest stipend can prepare you for managing a larger income in the future.
Most importantly, remember that an internship is a stage in your professional journey. Use the period not only to earn the stipend but also to acquire experience, build relationships, strengthen your CV and prepare for the next chapter of your teaching career.