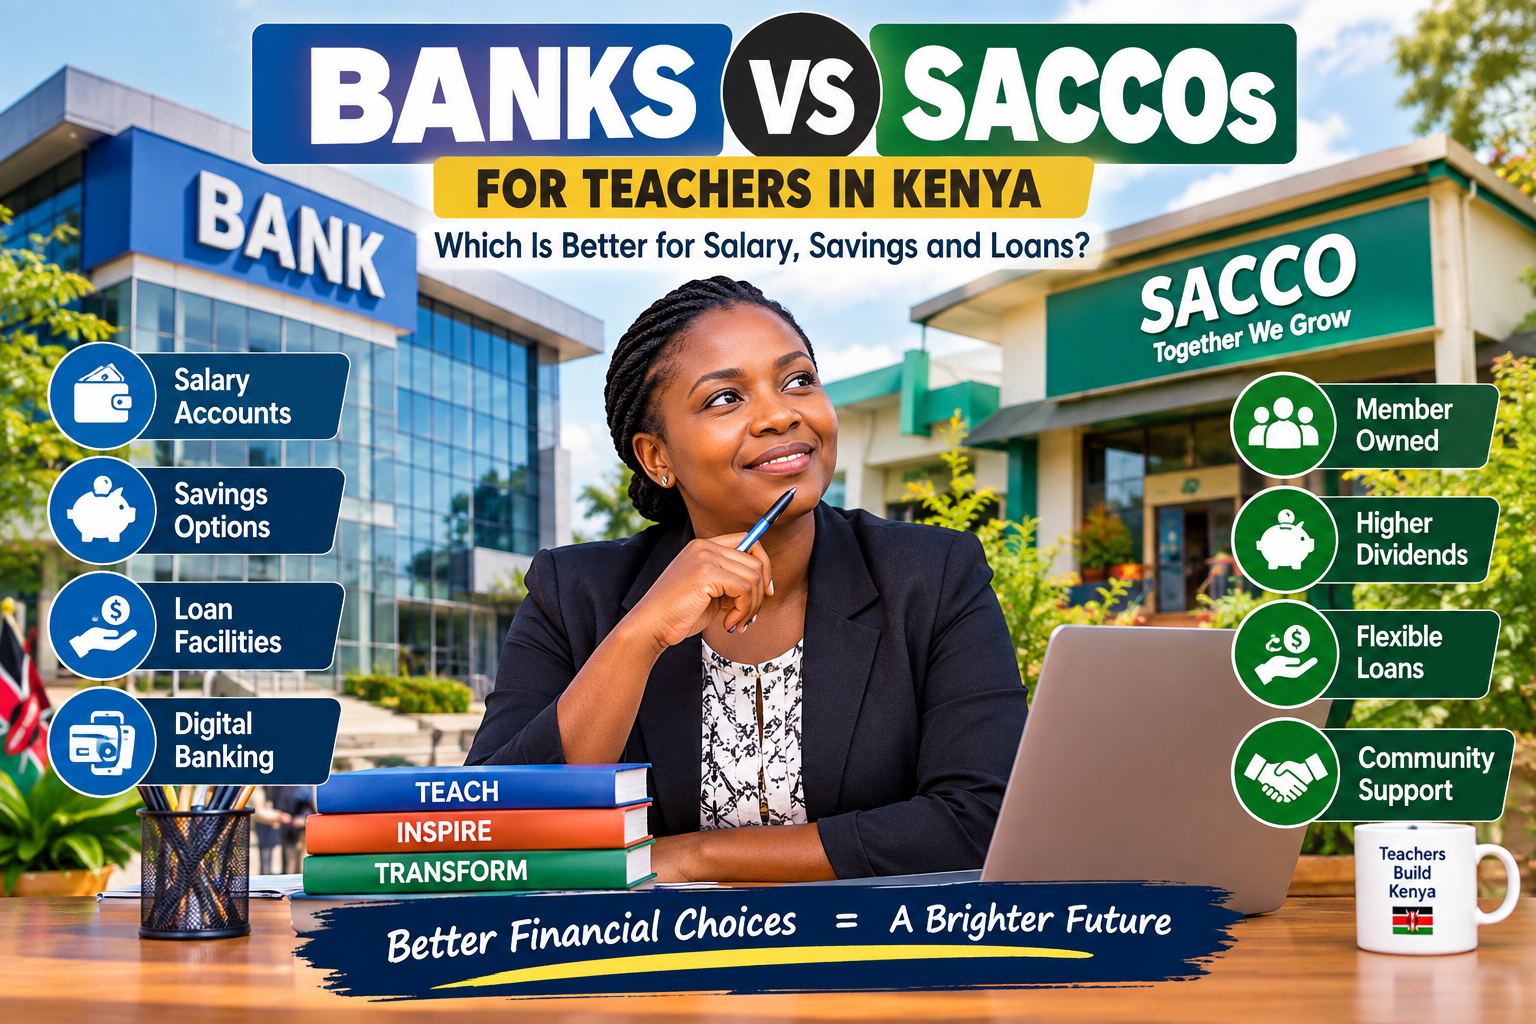
Introduction: Banks vs SACCOs for Teachers in Kenya
For teachers in Kenya, managing a monthly salary involves much more than simply receiving money and paying bills.
A teacher may need to save for a home, buy land, pay school fees, build rental houses, start a business, purchase a vehicle, prepare for retirement or deal with an unexpected financial emergency.
This is where the choice between a commercial bank and a SACCO becomes important.
Commercial banks and SACCOs provide different financial services and operate under different models. A bank can be convenient for receiving a TSC salary, making payments, using ATMs and accessing digital banking services. A SACCO, on the other hand, can provide a structured environment for saving, building member deposits and accessing member-based loans.
For many teachers, the question should not necessarily be:
“Should I choose a bank or a SACCO?”
A more useful question is:
“What should I use my bank for, and what should I use my SACCO for?”
In many cases, a teacher can benefit from using both.
This comprehensive guide explains banks vs SACCOs for teachers in Kenya, including salary paypoints, savings, personal loans, development loans, emergency loans, land, construction, investment and long-term financial planning.
Bank vs SACCO: What Is the Difference?
Before deciding which option suits you, it is important to understand how banks and SACCOs work.
What Is a Commercial Bank?
A commercial bank is a financial institution that provides services such as:
- Salary accounts
- Savings accounts
- Current accounts
- Personal loans
- Asset financing
- Mortgages
- Debit cards
- ATM services
- Mobile banking
- Internet banking
- Money transfers
- Business banking
For a TSC teacher, a bank can be particularly useful as the account through which the monthly salary is received.
Banks also offer different types of credit depending on the customer’s income, credit profile and financial needs.
What Is a SACCO?
A SACCO is a member-owned cooperative financial organization.
SACCO members generally save money with the organization and may qualify for various financial products according to the SACCO’s rules.
SACCOs can provide:
- Savings facilities
- Shares
- Deposits
- Development loans
- Emergency loans
- School-fees loans
- Asset-financing facilities
- Investment-related financing
- Other member services
One of the important differences is that SACCO borrowing can be linked to member deposits, shares, guarantors and membership requirements, depending on the particular SACCO.
This makes the SACCO model different from ordinary commercial banking.
Banks vs SACCOs for Teachers: Quick Comparison
| Feature | Commercial Bank | SACCO |
|---|---|---|
| TSC salary paypoint | Excellent option | Depends on arrangement |
| ATM access | Usually extensive | Usually more limited |
| Branch network | Usually extensive | Varies |
| Mobile banking | Generally strong | Varies by SACCO |
| Salary advance | Available from some banks | May be available |
| Personal loans | Available | Available |
| Savings | Available | Core function |
| Shares | No | Yes, depending on structure |
| Dividends | Not normally applicable | May be paid according to performance/rules |
| Guarantors | Usually not required for standard salary loans | Often used |
| Savings-linked loans | Usually not the main model | Common |
| Development loans | Available | Often important |
| Membership requirement | No | Yes |
| Financial convenience | Generally high | Depends on SACCO |
| Long-term member relationship | Less central | Very important |
The exact products, rates and requirements vary from one institution to another.
Why Teachers Need Both a Bank and a SACCO
One of the biggest financial mistakes is assuming that one institution must perform every financial function.
A teacher can instead give each institution a specific role.
Bank
Use the bank for:
- TSC salary
- Daily expenses
- ATM withdrawals
- M-Pesa transfers
- Bill payments
- Digital transactions
- Salary-related services
- Certain short-term credit facilities
SACCO
Use the SACCO for:
- Regular savings
- Deposits
- Shares
- Long-term borrowing
- Development projects
- Investment
- Asset creation
This creates a simple financial structure:
TSC Salary → Bank → Budget → SACCO Savings → Investment/Assets
Best Bank for Teachers in Kenya
There is no single bank that is automatically the best for every teacher.
The appropriate bank depends on your location, salary, existing loans, banking needs and financial objectives.
Teachers can compare major banks such as:
- Equity Bank
- KCB Bank
- Co-operative Bank
- Absa Bank Kenya
- Stanbic Bank Kenya
- Standard Chartered Bank Kenya
- NCBA Bank
- Other banks offering suitable salary and lending products
When comparing banks, consider more than the advertised loan amount.
Look at:
- Salary account charges
- ATM availability
- Agent network
- Mobile banking
- Loan interest
- Processing fees
- Insurance
- Repayment period
- Total repayment
- Early settlement terms
- Loan consolidation options
Best SACCO for Teachers in Kenya
There is also no universal answer to which SACCO is best.
Teachers should compare SACCOs according to their specific objectives.
A teacher-focused SACCO may be particularly attractive because its products can be designed around the needs of educators.
One well-known example is Mwalimu National SACCO, which serves members in the education sector.
However, teachers should also examine other SACCO options available to them.
Before joining, investigate:
- Membership requirements
- Minimum monthly savings
- Share requirements
- Loan multiples
- Interest rates
- Guarantor requirements
- Withdrawal rules
- Dividends
- Fees
- Financial performance
- Loan repayment periods
- Development-loan conditions
Never join a SACCO solely because another teacher says it offers “big loans.”
Banks vs SACCOs for Teacher Loans
Loans are one of the biggest reasons teachers compare banks and SACCOs.
But the cheapest loan is not necessarily the one with the lowest advertised interest rate.
A teacher should compare the total cost of borrowing.
For every loan offer, ask:
- How much am I borrowing?
- What is the interest rate?
- How is interest calculated?
- What is the repayment period?
- What is the monthly installment?
- What are the processing fees?
- Is insurance required?
- Are there other charges?
- What is the total amount I will repay?
- What happens if I repay early?
These questions can reveal significant differences between two apparently similar loans.
How Bank Loans Work for Teachers
A bank may assess your loan application using factors such as:
- Monthly salary
- Net income
- Existing loans
- Credit history
- Employment status
- Employer
- Repayment ability
- Loan purpose
- Security, where applicable
- Existing relationship with the bank
A teacher receiving a regular TSC salary may therefore have access to salary-based financial products.
However, being employed by TSC does not automatically mean that every teacher qualifies for the same loan amount.
How SACCO Loans Work for Teachers
SACCO loans can work differently.
A SACCO may consider:
- Your membership period
- Deposits
- Shares
- Monthly contributions
- Existing loans
- Guarantors
- Ability to repay
- The specific loan product
Some SACCOs use a loan multiplier based on qualifying deposits.
For example, purely as an illustration:
Savings/deposits: KSh 300,000
If the SACCO’s applicable loan multiplier were 3 times:
Potential loan basis = KSh 900,000
This is only an example. Actual SACCO rules differ and may include additional requirements.
The Importance of SACCO Savings for Teachers
Saving with a SACCO can provide more than a place to keep money.
Regular savings may help create a financial foundation for future borrowing or investment.
Consider a teacher who saves:
KSh 10,000 per month
After one year:
KSh 120,000
After five years, before considering dividends or other returns:
KSh 600,000
That amount can become part of a broader plan for:
- Land
- Construction
- Business
- Rental property
- Education
- Emergency reserves
- Retirement
The exact benefits depend on the SACCO’s rules and financial performance.
Bank vs SACCO for TSC Salary
For most teachers, salary banking is one of the strongest reasons to maintain a commercial bank account.
A good salary account can provide:
- Convenient salary deposits
- ATM access
- Mobile banking
- Online transfers
- Bill payments
- Debit cards
- Agent services
- Access to salary-related credit products
However, teachers should compare account charges and services.
A bank with a large branch network may be particularly useful for teachers working far from major towns.
What Is a TSC Paypoint?
A salary paypoint is the bank account designated to receive your salary.
Changing your salary paypoint may be considered when:
- You want access to different banking services
- You want a different loan facility
- Your current bank has poor accessibility
- You want lower charges
- You want improved digital banking
- You want to consolidate financial services
Teachers should handle paypoint changes carefully and confirm that the new account has successfully received salary before closing the old account.
Banks vs SACCOs for Development Loans
Development loans are particularly important for teachers who want to build assets.
A development project may include:
- Building a home
- Constructing rental units
- Buying land
- Expanding a business
- Purchasing farming equipment
- Starting an income-generating project
Both banks and SACCOs may offer financing for these objectives.
The important question is not simply:
“Who will lend me more?”
Instead ask:
“Which financing structure allows me to complete the project without creating unsustainable monthly repayments?”
Bank vs SACCO for Building a House
Suppose a teacher wants to construct a house costing:
KSh 5 million
The teacher could investigate:
- Bank mortgage/development finance
- SACCO development loan
- Personal loan
- Combination of savings and borrowing
- Other legitimate financing options
A bank may offer longer-term property financing.
A SACCO may offer development financing based partly on membership and deposits.
Compare:
Loan amount + interest + fees + insurance + repayment period + total repayment
before deciding.
Bank vs SACCO for Buying Land
Land is another major financial goal among Kenyan teachers.
Before borrowing to buy land, calculate the complete project cost.
For example:
Land purchase price
- Legal fees
- Valuation
- Transfer costs
- Loan costs
- Other transaction expenses
Do not assume that the advertised land price is the total amount you need.
A teacher should also verify the property’s documentation and conduct appropriate due diligence before committing borrowed money.
Bank vs SACCO for School Fees
School fees are a common reason salaried workers borrow.
A teacher may compare:
- SACCO school-fees loan
- Bank personal loan
- Salary advance
- Emergency facility
- Personal savings
The key issue is repayment.
If school fees are an annual expense but the loan continues for several years, the teacher could end up paying interest long after the original school bill has been settled.
Where possible, building a school-fees savings fund can reduce dependence on emergency borrowing.
Bank vs SACCO for Emergency Loans
Both banks and SACCOs can provide emergency financing.
Bank emergency/salary facility
Potential advantages:
- Speed
- Digital access
- Existing salary relationship
- Convenience
SACCO emergency facility
Potential advantages:
- Existing membership
- Savings relationship
- Member-focused products
- Potentially convenient access
Before taking emergency credit, determine whether the problem is genuinely temporary.
If you borrow every month to pay for food, transport or household bills, increasing your debt may not solve the underlying cash-flow problem.
Bank vs SACCO for Buying a Car
A teacher planning to buy a vehicle should compare:
- Bank asset finance
- SACCO vehicle loan
- Personal loan
- Cash savings
Asset financing can have different conditions from ordinary personal borrowing.
Consider:
- Deposit requirement
- Loan period
- Interest
- Insurance
- Valuation
- Registration
- Monthly repayment
- Maintenance costs
Remember that owning a car involves expenses beyond the purchase price.
Bank vs SACCO for Starting a Business
A teacher may want to start:
- A retail shop
- Agribusiness
- Rental property
- Transport business
- Online business
- Poultry project
- Dairy farming
- Other income-generating activities
Before taking a loan, prepare a basic business plan.
Calculate:
Expected income – operating expenses – loan repayment = expected surplus
If the business cannot comfortably service the loan under realistic assumptions, borrowing may create additional financial pressure.
Guarantors: A Major Difference for SACCO Members
Guarantors are an important feature of many SACCO loan arrangements.
A guarantor may agree to support a member’s loan under the SACCO’s rules.
This creates responsibility for both parties.
Before guaranteeing another person’s loan, understand:
- The amount guaranteed
- Your potential liability
- How long the guarantee remains
- What happens if the borrower defaults
- How you can be released from the guarantee
Likewise, borrowers should not treat guarantors as an unlimited source of credit.
Which Is Better for Saving: Bank or SACCO?
For simple everyday savings, a bank can be convenient.
For structured long-term member saving, a SACCO may offer additional features such as deposits and shares depending on its structure.
The right choice depends on your objective.
Short-term emergency savings
A highly accessible savings account can be useful.
Long-term investment savings
A SACCO or other investment vehicle may be considered as part of a broader financial plan.
Retirement
Teachers should think beyond ordinary savings and consider a diversified long-term retirement strategy.
Understanding SACCO Shares and Deposits
Teachers joining a SACCO should understand the difference between:
Shares
and
Deposits/savings.
They may have different purposes and different withdrawal or transfer rules.
Never assume that all money deposited with a SACCO can be withdrawn immediately.
Read the SACCO’s current rules carefully.
What About SACCO Dividends?
Some SACCOs distribute dividends on qualifying shares or returns on deposits according to their policies and annual performance.
However:
Past dividends do not guarantee future dividends.
A teacher should examine the SACCO’s financial statements, governance, fees, loan performance and overall financial health rather than focusing only on the previous year’s dividend.
Can a Teacher Have Both a Bank Loan and SACCO Loan?
A teacher may have multiple financial obligations, subject to applicable rules and the lender’s assessment.
However, having access to several loans does not mean that taking all of them is financially wise.
Before adding another loan, calculate:
Net salary – existing deductions – new loan repayment = remaining income
Ask yourself whether the remaining amount can comfortably cover:
- Food
- Housing
- Transport
- Utilities
- School expenses
- Medical needs
- Savings
- Emergencies
A large loan can significantly reduce financial flexibility.
How Much Should a Teacher Borrow?
Do not automatically borrow the maximum amount offered.
Instead, determine the actual amount required.
For example, if a construction project needs:
KSh 1.8 million
there may be little reason to borrow:
KSh 3 million
simply because the lender approves it.
Borrowing more means paying more interest and increasing monthly obligations.
The best loan amount is generally determined by the project requirement and sustainable repayment capacity, not the maximum amount a lender is willing to offer.
How to Compare Bank and SACCO Loan Offers
Use this checklist.
| Item | Bank | SACCO |
|---|---|---|
| Loan amount | Compare | Compare |
| Interest rate | Compare | Compare |
| Repayment period | Compare | Compare |
| Monthly installment | Compare | Compare |
| Processing fee | Compare | Compare |
| Insurance | Compare | Compare |
| Guarantors | Check | Check |
| Collateral | Check | Check |
| Total repayment | Compare | Compare |
| Early settlement | Check | Check |
The total repayment is one of the most important figures.
Example: Comparing a KSh 2 Million Loan
Imagine a teacher wants to borrow:
KSh 2,000,000
The teacher obtains two hypothetical quotations.
Bank
Loan: KSh 2,000,000
Term: 60 months
Monthly payment: quotation required
Processing fee: quotation required
Insurance: quotation required
SACCO
Loan: KSh 2,000,000
Term: 60 months
Monthly payment: quotation required
Processing fee: quotation required
Guarantors: required according to rules
The teacher should not decide based on the headline interest rate.
Request a complete repayment schedule from both institutions.
Then compare the total amount paid over the entire loan period.
The Best Strategy for a TSC Teacher
For many teachers, a practical financial structure can look like this:
Step 1: Receive salary through a convenient bank
Use the bank for salary and daily financial transactions.
Step 2: Create a monthly budget
Know exactly where your salary goes.
Step 3: Save consistently
Send a predetermined amount to your SACCO or savings/investment account.
Step 4: Build an emergency fund
Try to avoid using expensive credit every time an unexpected expense appears.
Step 5: Borrow for productive purposes
Where possible, use major borrowing to support assets or projects that fit your financial plan.
Step 6: Control debt
Do not keep adding loans simply because you qualify.
Step 7: Build assets
Work toward:
- Land
- Home
- Rental property
- Business
- Investments
- Retirement savings
Common Mistakes Teachers Should Avoid
Mistake 1: Choosing a bank because it offers the biggest loan
A bigger loan can mean a bigger repayment burden.
Mistake 2: Looking only at the interest rate
Fees, insurance and repayment period also matter.
Mistake 3: Ignoring SACCOs
Teachers should compare SACCO financing with bank financing for major projects.
Mistake 4: Taking loans for consumption
Repeated borrowing for ordinary expenses can create a debt cycle.
Mistake 5: Guaranteeing loans without understanding the risk
A guarantor can have financial responsibilities if the borrower defaults.
Mistake 6: Saving nothing
A teacher who uses the entire salary every month may remain financially vulnerable even with a good income.
Mistake 7: Borrowing the maximum available
Approval is not the same as affordability.
Bank vs SACCO: Which Is Better for Teachers?
The answer depends on the purpose.
For TSC salary:
Bank
For everyday banking:
Bank
For ATM and digital transactions:
Bank
For structured member savings:
SACCO
For savings-linked borrowing:
SACCO may be useful
For large development projects:
Compare both
For emergency credit:
Compare the actual cost and speed
For long-term wealth building:
Use saving, investment and carefully managed borrowing together
A Two-Institution Strategy for Teachers
Instead of thinking bank versus SACCO, consider:
BANK
Salary + daily expenses + payments + convenient banking
↓
SACCO
Savings + deposits + shares + long-term borrowing
↓
INVESTMENTS
Land + house + business + rental property + retirement
This approach separates everyday spending from long-term financial development.
Frequently Asked Questions About Banks and SACCOs for Teachers
Is a SACCO better than a bank for teachers?
Neither is universally better. Banks are generally useful for salary banking and everyday financial services, while SACCOs can be useful for structured savings and member-based borrowing. The right choice depends on the teacher’s financial objective.
Which is better for TSC salary?
A commercial bank is generally convenient for receiving TSC salary because of its banking infrastructure, ATM network, mobile services and payment facilities. Teachers should compare the charges and services of individual banks.
Which gives teachers bigger loans?
Loan limits vary by institution and individual borrower. A bank may assess salary and repayment ability, while a SACCO may also consider deposits, shares, membership and guarantors.
Can a teacher belong to a SACCO and have a bank account?
Yes. In fact, using a bank and SACCO for different purposes can provide a practical financial structure.
Can teachers have both bank and SACCO loans?
A teacher may have multiple financial obligations subject to applicable payroll, affordability and lender requirements. Before taking another loan, calculate the effect on take-home salary.
Which is better for building a house?
Compare the development or property financing available from both banks and SACCOs. Consider the interest, fees, repayment period, security and total repayment.
Which is better for buying land?
Both may provide relevant financing. Compare the actual loan offers and remember to budget for legal, valuation, transfer and other transaction costs.
Are SACCO dividends guaranteed?
No. Any dividends or returns depend on the SACCO’s performance and applicable rules. Past performance should not be treated as a guarantee of future returns.
Should a teacher move their salary to a bank because of a loan?
Not automatically. First obtain the complete loan quotation and compare it with your existing bank and SACCO options.
What is more important: a large loan or a low repayment?
Neither should be considered in isolation. A teacher should examine the loan’s total cost, repayment period and effect on monthly cash flow.
Final Conclusion: Bank or SACCO?
For Kenyan teachers, the bank-versus-SACCO debate does not have to be an either-or decision.
A bank can provide the convenience needed for receiving a TSC salary, making payments, accessing ATMs, using mobile banking and managing everyday finances.
A SACCO can provide a structured approach to saving, building deposits and shares, and accessing member-based financing for projects such as land, construction, business and investment.
For many teachers, the practical approach is:
Bank for salary and everyday banking.
SACCO for structured saving and long-term financial development.
Compare both when taking a major loan.
The most important financial decision is not finding the institution that offers the largest loan. It is finding financing that you can repay while still maintaining a healthy monthly budget and continuing to build wealth.
Before taking any major loan, compare the interest rate, fees, insurance, repayment period, monthly installment and total repayment. Also consider your existing deductions and future financial goals.
A teacher who combines disciplined saving, careful borrowing and long-term investment can use both banks and SACCOs as tools for building financial security rather than allowing debt to control their salary.